


 Remgro offices in Stellenbosch. (Photo: Stellenbosch Heritage Foundation / Wikipedia)
If you looked at Remgro’s share price over the past year you would be forgiven for thinking that the market has become a lot more enthusiastic about the management team’s capital allocation strategy.
After all, Remgro is up 22%, while the intrinsic net asset value (iNAV) is only up by 4.6%.
This deserves a closer look though, since there are interesting reasons for this divergence.
Before we get to that, it’s important to understand what the iNAV is and what it tells us about an investment holding company like Remgro.
This acronym stands for intrinsic net asset value. This is management’s view of what the assets in the company are worth, net of debt and an allowance for tax that would be paid if the assets were sold. For an investment holding company, this is the key metric to consider.
In theory, if the market agreed with management on all the underlying values, then the share price would still trade at a modest discount to iNAV. The reason for the structural discount is that the market needs to make allowance for the costs of having the holding company structure (director fees and the like).
But where the market disagrees with management, or where there are concerns around how capital might be allocated by that team, the discount tends to open up.
For context, Remgro’s iNAV per share is R305.80, yet the share price is trading at around R206. That’s a discount to iNAV of roughly 33%. The discount has been in the 40s before, so Remgro has actually managed to close the discount to some extent. This is thanks to the share price achieving much better growth in the past year than the iNAV.
Before claiming this as a famous victory, it’s worth noting that rival company Sabvest is trading at a discount of just 12%.
To understand the difference, we need to look at two things: the underlying assets and the way in which management allocates capital.
When calculating iNAV, things are very simple if the portfolio has listed assets with observable prices. When there are unlisted assets, directors will apply their own valuation methodology per asset and will explain the approach in the financials.
The investment gap
Now, you may be tempted to conclude that a portfolio of listed assets would trade at a smaller discount, as investors have visibility over the calculation. But in practice, because investors are able to buy those listed assets directly instead of via the investment holding company, a portfolio of listed assets tends to drive a larger discount to the iNAV.
At Sabvest, almost the entire portfolio sits in unlisted assets. At Remgro, the listed assets contributed 34.2% of iNAV in the latest period. Investors don’t need to go via Remgro to get exposure to OUTsurance, Rainbow and RCL Foods as the major listed investments.
Another reason for the structural difference in discounts is that Remgro is stubbornly attached to paying dividends. Despite the share price continuing to trade at a substantial discount to iNAV, Remgro used a period of strong cash flow as justification to pay a special dividend of 550 cents per share (in addition to the ordinary dividend of 595c per share).
Whether management teams like it or not, this sends two clear messages to the market. The first is that Remgro appears to be short on attractive investment opportunities, so they would rather return the cash to investors. The second is that the management team doesn’t appear to have conviction in their iNAV, otherwise why wouldn’t they repurchase shares at a 33% discount to what they believe the company is worth?
As you can imagine, these messages aren’t viewed in a bullish light.
Conversely, Sabvest makes frequent use of share buybacks to invest in its own shares at prices that represent a discount to the intrinsic value. This strategy helps keep the discount at bay, since a wider discount leads to more repurchases and thus support for the share price.
But then why did Remgro’s discount to iNAV close over the past year if the company is paying special dividends instead of repurchasing shares?
There can be many reasons, but one plausible explanation is that the shape of Remgro’s iNAV has changed. These days, the largest contributor to group headline earnings is Mediclinic, having grown those earnings by a whopping 23.6% in the past year. Remgro took Mediclinic private, so investors can’t get access to Mediclinic other than via Remgro shares. Like at Sabvest, this exposure to an unlisted asset helps reduce the discount.
Over the past year, Remgro’s listed assets fell in value by 8.3%. Their contribution to group iNAV after tax dropped from 39.1% to 34.2%. But the unlisted assets were only up by 1% overall, so their contribution to group iNAV fell from 57.5% to 55.4%.
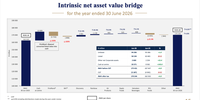
But if iNAV was up by 4.6%, then what are we missing here?
The answer lies in the cash at the centre, up by 143% and contributing about 12% of iNAV vs 5.1% in the comparable period. Adjusted free cash flow at the centre increased by 28.6% on a per-share basis, with the rest of the jump explained by corporate activity and asset disposals.
In other words, the Remgro iNAV is significantly more concentrated in cash than before. The market doesn’t have to guess what the cash is worth, or how easily it can be realised. It’s simply there and ready to be allocated in a useful way.
But if the approach is to pay special dividends, then the cash pile will be reduced over time and the proportion of listed and unlisted assets in the iNAV will increase once more. The alternative is to use share buybacks, which would reduce the number of shares in issue while getting the cash off the balance sheet.
If Remgro took this approach, then there are good arguments to be made that they would help avoid the discount returning to the 40s.
Unfortunately for investors, Remgro is far more interested in paying large dividends than repurchasing shares.
The company generated great returns in the past year, but one is left wondering what might have been the case if they had done buybacks along the way instead. DM
Comments
Scroll down to load comments...