


 Photo supplied
For decades, investment discussions have centred on a familiar question: Which portfolio delivers the highest return?
For trustees responsible for a default investment portfolio, that question is important, but incomplete.
A portfolio can produce strong long-term returns and still expose members to severe losses along the way. Trustees are choosing a default for a membership that is anything but uniform. Younger and older members, those early in their savings journey and those approaching retirement, will not experience the same market loss in the same way.
A portfolio’s headline return therefore tells only part of the story. The analysis below considers long-term growth alongside the downside associated with achieving it.
Return is only one part of the picture
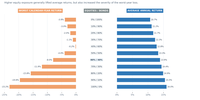
Our analysis of 25 complete calendar years of South African equity and bond returns illustrates the trade-off.
We used the FTSE/JSE All Share Index (ALSI), a broad measure of South African listed equities, and the FTSE/JSE All Bond Index (ALBI), which tracks the domestic bond market, to model portfolios ranging from 100% bonds to 100% equities.
The result is straightforward: as equity exposure increased, average returns improved, but losses in the worst years also became more severe.
A 100% equity portfolio delivered the highest average annual return of 16.0%, but its worst calendar-year decline was -23.2%. By comparison, a 60/40 equity-bond portfolio delivered an average annual return of 13.9%, while its worst calendar-year decline was -8.0%.
The difference in average return was therefore accompanied by a substantial difference in the severity of the worst annual loss.
The comparison illustrates the trade-off between return and downside. Greater equity exposure was associated with higher average historical returns, but also with deeper losses when markets fell.
The analysis does not identify a single correct default allocation. It shows why historical return provides only one measure of how different allocations behaved over the period.
Downside has a recovery cost
The size of a loss matters for another reason: losses and gains are not symmetrical. A portfolio that falls 23% requires a gain of nearly 30% simply to get back to where it started.The deeper the loss, the greater the return required to recover it.
For members, that can mean more time is needed to regain lost ground. For a fund, a severe decline can also create pressure around a strategy at precisely the point when markets are under strain.Periods of poor performance can prompt members to consider switching, lead advisers to question a strategy and place trustee boards under pressure to respond to recent losses.
Downside is therefore more than a number on a performance report. It can influence how a default strategy is experienced during difficult markets.
The significance of that downside will differ from fund to fund, depending on factors including the fund’s return objective, membership profile, investment horizon and the role of the default portfolio.
Investment risk remains part of pursuing long-term growth. The analysis simply highlights the importance of understanding the losses that accompanied different levels of historical return.
Diversification changes the experience
The analysis also shows how diversification can reduce the severity of losses.
Over the 25-year period, a portfolio comprising 40% equities and 60% bonds experienced a maximum calendar-year decline of just 0.2%. That period included the Dot-Com collapse, the Global Financial Crisis, the COVID-19 shock and a number of South African economic and political crises.
This does not mean lower equity exposure is automatically more suitable. Different funds have different objectives, membership profiles and investment horizons, while members also require exposure to assets capable of generating long-term growth.
What the historical comparison does show is that introducing bonds materially changed the severity of losses experienced by the portfolios analysed.
Regulation 28 sets limits and requirements around the assets retirement funds may hold and forms part of the framework within which retirement-fund portfolios are constructed. Compliance with those requirements does not, on its own, determine the suitability of a particular default portfolio for a particular membership.
The historical results instead provide another lens through which different allocations can be considered: what they returned, how severely they fell and what recovery from those losses required.
A 60/40 portfolio may produce very different outcomes from a portfolio with more or less equity exposure. The 60/40 comparison is not presented as a recommended allocation. Its purpose is to illustrate how differences in asset allocation can affect both historical return and downside.
Looking beyond the return number
Historical performance remains relevant, but the 25-year comparison shows that return figures do not tell the whole story.
Higher equity exposure was associated with higher average returns, but also with deeper losses in the worst years. Those losses, in turn, required larger subsequent gains simply to recover lost ground. Diversification materially changed that experience across the portfolios analysed.
The evidence does not establish an optimal equity-bond allocation or prescribe a default portfolio. The appropriate allocation will depend on the circumstances and objectives of each fund.
What the analysis shows is narrower, but important: portfolios that produced different levels of historical return also exposed investors to very different experiences when markets fell.
Return and downside are therefore two parts of the same historical picture. DM
Old Mutual Corporate Consultants works with retirement-fund boards and management committees to define investment objectives, assess portfolio strategy and review its ongoing suitability. For more information about Old Mutual Corporate Consultants and its investment consulting services, contact the Old Mutual Corporate Consultants team or email omccenquiries@oldmutual.com.